Renters Insurance: Personal Property, Liability and Common Exclusions
Compare US renters insurance coverage for belongings, liability and temporary accommodation, with practical questions about limits, exclusions and claims.
On this page
- Separate the landlord’s building from your belongings
- Build an inventory before choosing a limit
- Compare settlement terms as well as the premium
- Do not confuse water damage with flood cover
- Check the people and activities covered
- Plan for the first few days after a loss
- Common questions
- Sources and references
A renters policy can protect several very different parts of your finances. The amount available for belongings does not tell you how much liability protection you have, and neither number tells you whether a temporary move would be covered. Start with the events you want to protect against, then examine the separate sections of the contract. This guide concerns US renters insurance; policy wording and state rules determine an individual claim.
Separate the landlord’s building from your belongings
The California Department of Insurance residential insurance guide explains that a landlord does not insure a tenant’s personal possessions through the landlord’s building coverage. It identifies personal property, loss of use, liability and medical payments to others as distinct renters coverages. Those categories are a useful starting point, but do not copy the guide’s illustrative limits into an application without checking your own policy.
Imagine arriving home after a covered kitchen fire. The building owner might arrange repairs to walls and wiring. You would still need to work out who pays for your damaged clothes, whether a hotel is reimbursable, and what happens if someone alleges that you caused their loss. These are separate questions. A certificate supplied to a property manager should not be treated as proof that every one of them has been answered.
Four questions, four policy sections
- What was damaged? Check personal property coverage and special limits.
- Can you stay at home? Read the loss-of-use trigger and allowance.
- Is someone making a claim against you? Review personal liability and exclusions.
- Was a visitor injured? Ask how medical payments differs from liability.
Build an inventory before choosing a limit
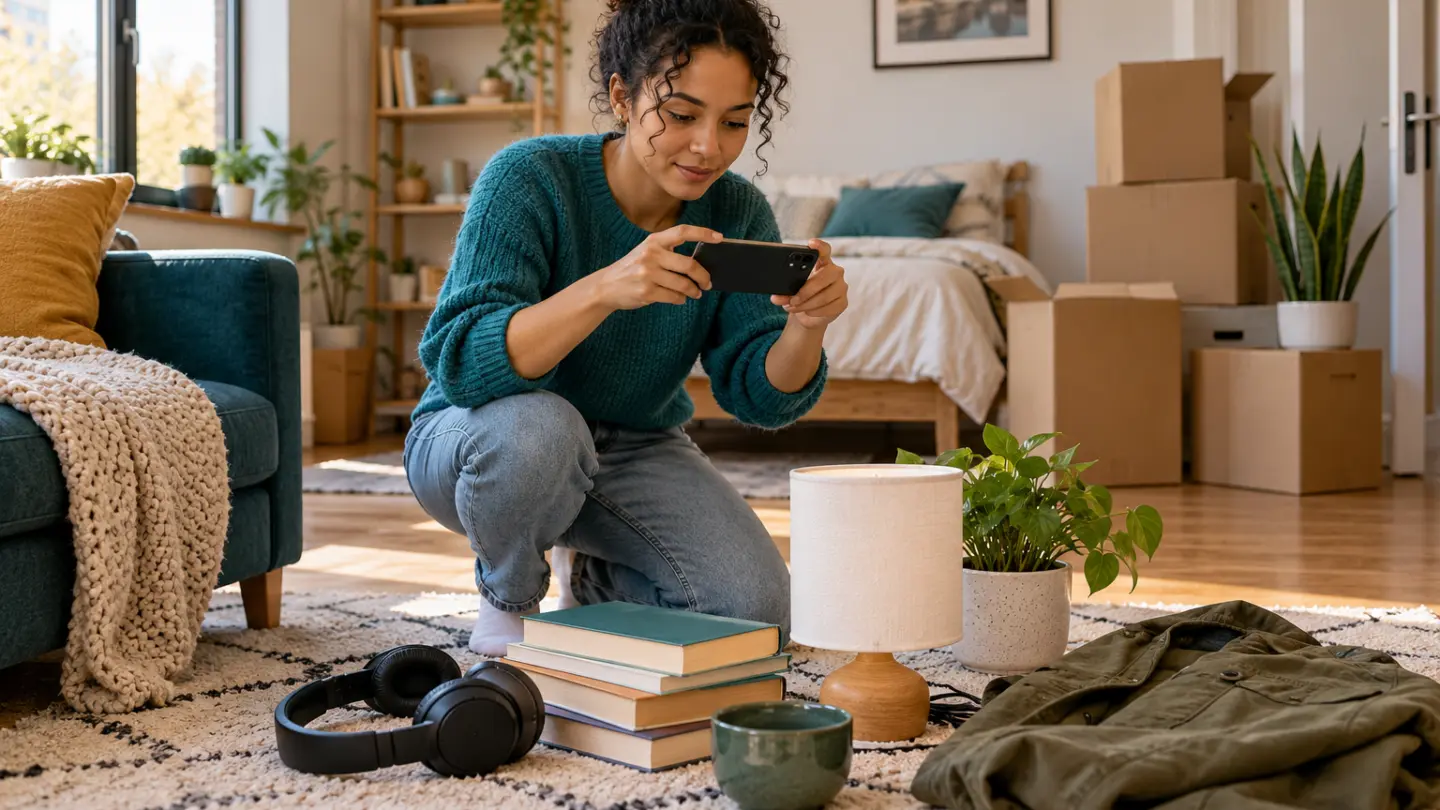
For a practical first pass, walk through one room at a time and list the belongings you would actually need to replace. Include the less memorable things: bedding, cookware, shoes, small appliances and work furniture. Put a current replacement estimate beside each group, then record which figures you have checked and which are rough guesses. The result is a discussion document for quotations, not a valuation certificate or a guaranteed settlement.
For example, suppose your own inventory totals $3,200 for furniture, $1,400 for electronics, $1,100 for clothing and $800 for kitchen and household items. The sum is $6,500. If you later discover a $900 bicycle and $600 of tools were omitted, the inventory becomes $8,000. These invented amounts illustrate why a quick glance around a room can miss important costs; they are not estimates of what a typical household owns.
Save photos, model numbers and available receipts somewhere you can access away from the apartment. For valuable jewelry, the NAIC’s guidance on jewelry within home and renters insurance highlights the possibility of limited coverage and the value of photographs and appraisals. Ask specifically about an item that would be expensive or difficult to replace, rather than assuming the overall property limit settles the question.
Compare settlement terms as well as the premium
A low premium can conceal a difference in what an insurer would pay after a covered loss. The Texas Department of Insurance renters guide distinguishes replacement-value coverage from settlement that takes depreciation into account. Ask which basis applies to your belongings, whether you must replace an item to receive the full eligible amount, and what evidence or deadlines apply.
Use the same inventory and deductible when asking several insurers for quotations. Then request a second quotation if you want to see the effect of changing one feature. Changing the property limit, deductible and settlement basis simultaneously makes it hard to identify what produced the saving. Our explanation of replacement cost and actual cash value provides a worked comparison, although a renters contract must be checked on its own terms.
| Question | What to record | Why it matters |
|---|---|---|
| Property | Limit, deductible and settlement basis | Shows how belongings are treated |
| Valuables | Item or category sublimits and endorsements | A large total limit may not remove smaller restrictions |
| Temporary accommodation | Covered trigger, amount and time limit | Separates a disrupted home from a reimbursable expense |
| Liability | Limit, insured people and exclusions | Clarifies whose activities are protected |
| Administration | Annual total, instalment costs and cancellation terms | Makes payment options comparable |
Do not confuse water damage with flood cover
The cause of water damage matters. A burst pipe and water entering during a flood are not interchangeable descriptions of a loss. The Texas insurance regulator’s renter flood guidance explains that ordinary renters insurance does not cover flood damage and that a separate flood policy can cover a renter’s belongings. Ask about the relevant options before an event is imminent, including eligibility, exclusions and when coverage would begin.
A useful question to send an insurer is: “For this address, how would my proposed policy treat water from plumbing, a sewer backup and an external flood?” Request the relevant sections, not just a broad reassurance about water protection. Also ask about earthquakes and other locally important hazards. You do not need to become a claims specialist; you need a written account of the important gaps before deciding what risk you can carry yourself.
Check the people and activities covered
List everyone who lives in the home and explain whether they are family members, partners, lodgers or unrelated roommates. Give accurate information about pets, working from home and any business equipment. Ask the insurer who would be insured and whether any activities require additional cover. Avoid assuming that splitting a rent payment automatically means splitting a policy, or that a roommate’s claim would be treated as your own.
Consider a shared apartment with two unrelated renters who each own a laptop. An inventory containing both devices does not establish that both owners are insured. The application, named insureds and policy definitions need to support the arrangement. Have each person retain the documents relevant to their own protection, and clarify what happens when somebody moves out before the renewal date.
A practical decision sequence
Inventory → exclusions → people → quotation → final documents. Estimate what you own, identify important uncovered events, confirm who is insured, compare matching quotations, then check that the issued contract matches the arrangement you accepted.
Plan for the first few days after a loss
Think about the cash you might need before a claim is settled. In a hypothetical covered loss with an eligible $2,400 property settlement and a $500 deductible applied to that settlement, subtraction leaves $1,900. That simplified example does not account for sublimits, depreciation, other deductibles or settlement conditions. It shows why the deductible should be an amount you can realistically manage, rather than merely a lever for lowering the premium.
Keep the claims contact, policy number and inventory together. If a loss occurs, follow the insurer’s reporting instructions and keep records of conversations, damage and relevant spending. Ask before discarding damaged items when it is safe to retain evidence. For temporary accommodation, distinguish ordinary living expenses from additional costs and ask what documentation is required. Do not assume every hotel booking or restaurant bill will be reimbursed.
Finally, review the policy when you move, acquire valuable items or change household arrangements. Put the premium and a manageable emergency reserve into your monthly budget. A useful renters policy is one whose limits and exclusions you understand before needing it, with records that make a future claim easier to explain.
If a protection package also advertises appliance repairs, our comparison of home insurance and home warranties explains why a service contract should be examined separately from property insurance.
Common questions
Does my landlord’s insurance replace my belongings?
Do not assume it does. The landlord’s building coverage and your personal possessions are different interests. Ask to see what your own renters policy covers, including the property limit and settlement terms. A lease requirement or proof-of-insurance document should be checked alongside the actual policy, rather than used as a substitute.
How do I choose a personal property limit?
Start with a room-by-room inventory and current replacement estimates for the things you own. Include small everyday items as well as expensive purchases. Discuss the total with the insurer, then check category limits for valuables. An inventory estimate helps a conversation; it does not override the conditions of a claim.
Is replacement cost always paid immediately?
Ask the insurer about its settlement process. A policy may have conditions about replacing an item, submitting evidence or meeting deadlines before the full eligible payment is available. Record those conditions when comparing quotations so you understand both the eventual benefit and the cash you might need in the meantime.
Will a policy cover an unrelated roommate?
That depends on the named insureds, definitions and terms of the particular contract. Tell the insurer who lives in the property and ask for written confirmation about each person’s status. Sharing rent, an address or a belongings spreadsheet does not by itself establish that somebody is insured under your policy.
Does renters insurance include flood protection?
Ordinary renters insurance generally does not cover flood damage. A separate flood policy may offer contents protection for renters. Ask about your address, eligible belongings, waiting periods and exclusions before buying. Do not treat plumbing leaks, sewer backup and external flooding as the same event when discussing possible water damage.
What should I ask about a valuable ring?
Ask about the applicable jewelry limit, the events covered and whether separately scheduling the ring would change protection. Keep photographs and any requested appraisal. Explain whether you need protection away from home as well. The overall personal property limit may be much larger than the amount available for an individual valuable.
Does loss of use pay all my living expenses?
Read its trigger, eligible expenses, maximum amount and time limit. Ask how the insurer distinguishes additional expenses from your normal spending and what receipts it needs. A temporary move can be expensive, but the fact that you incurred a cost does not automatically make that cost reimbursable under the policy.
Is the highest deductible the cheapest choice overall?
It may reduce the quoted premium, but it also changes what you must fund when the deductible applies. Compare the premium difference with the additional amount you would need after a loss. Keep other coverage features constant during that comparison, and choose a deductible that fits your available cash rather than guesswork.
Should I include equipment used for work?
Tell the insurer about work activities and equipment, including who owns the equipment and whether you receive clients at home. Ask about business-related exclusions or limits and whether additional coverage is needed. Describing something as a personal laptop in an inventory does not resolve how the policy treats its actual use.
When should I review an existing policy?
Review it before moving and when household members, valuable belongings or activities change. Also compare the renewal documents with the previous contract for changes in price or protection. Keep your inventory accessible away from the rental property, and ask the insurer to explain any unfamiliar amendments before the renewal becomes effective.